

Getting to Know: Rosemary Hassan

Who are you and what do you do?
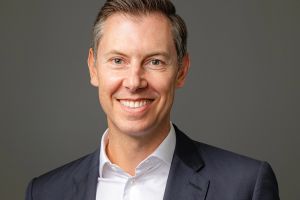
I am Rosemary Hassan an AFA and CFP practitioner. I work at Hassan & Associates, a company established together with my husband, Simon Hassan, more than 21 years ago, and which is currently working through the implementation of our business succession plan.
How did you get into the industry?
My career (although I had no idea this would be my career then), began 40 years ago when I worked as a financial adviser in the UK. This role, in comparison with today's adviser, was very "raw and unregulated". Knocking on doors, completing a data collection booklet, and encouraging people to save into a market linked unit trust. I introduced many families to the concept of compound interest, encouraging long-term saving into the same market where we ourselves shop as well as introducing bank accounts so as to transfer regular savings directly to their long-term savings plan (unit trust). My biggest competition in business at this time was "The man from the Pru". He collected the premiums door-to-door and promised a very large sum after a certain period of time. I found this an easy win, teaching clients to share in the market's growth as opposed to save a very little amount into a closed box endowment plan, losing the buying power of their pennies when it came time to access them.
If there is one thing you would like to change about the financial advice industry, what would it be?
Call me old-fashioned, but I still call upon my experiences of 40 years ago when it comes to sitting in front of clients (new or otherwise). "Client first" goes without saying, and the change I would like to see is the financial advice industry thriving on a good reputation. It seems this profession is always clambering over a misconception that financial advisers behave badly. Listening to and reading our industry reporters, it seems that this is still largely how the general public perceives us. It seems odd to think that currently so much effort and money is being spent on discussing and writing a "client first" code of conduct. The regulator, our professional body, and our own actions and behaviours: (all of these) should be our advocate to the general public on this point. With the current amount of compliance and required disclosures, clients by now, should be able to feel comfortable with their choice of adviser, whether from a large institution or small financial planning practice. I'd like the regulator to be more proactive in being an advocate of the NZ financial advice industry.
What’s the best advice you have ever received?
"Measure twice, think three times, and cut once." I was 10 years old and it made perfect sense. Thanks Dad.
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.