

Pathfinder Commentary: Portfolio protection
This leaves these portfolios fully exposed to market downturns. There are, however, a number of ways active and passive portfolios can protect against market falls. This note explains some approaches to equity portfolio protection – and considers the benefits and costs (both explicit and implicit) for each.
Beta basics
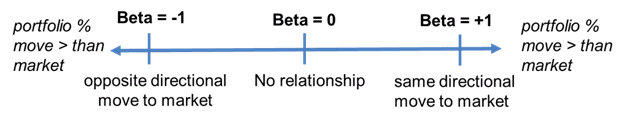
First, some market basics for understanding protection strategies. The measure by which a portfolio’s value rises or falls as the market rises or falls is called “beta”. Beta is a measure of how correlated the portfolio is relative to the market (do they move in the same or different directions?) and the size of the move relative to the market (does the portfolio move by more or less than the market?).
Positive beta implies that the portfolio and market move in the same direction. For instance, a beta of 1 would suggest there is no difference between moves by the portfolio and the wider market. Negative beta is the converse – the portfolio tends to fall as the market rises, and rises as the market falls. A high beta (>1 or <-1) implies that the portfolio moves by more than the wider market. And to complete the confusion, zero beta means there is no relationship between market and portfolio moves. The beta for portfolio movements compared to the market is represented below:
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.