

RBNZ ponders re-insurance clampdown
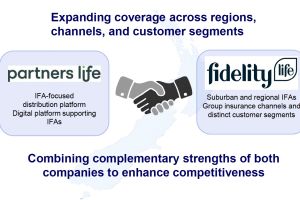
Some insurance companies, such as Partners Life, are backed by re-insurance. When a policy is sold, the re-insurer pays a proportion of the associated sales and issue costs. In return, they receive that same proportion of the premiums, less an expense allowance, and pay the same proportion of claims.
Re-insurers use their substantial capital bases to fund insurers who would otherwise have to raise significant amounts of capital.
But the Reserve Bank has asked for submissions on whether there is a real risk transfer involved, or whether the deal is a loan and should be reflected in insurance companies’ accounts as such.
Some insurance companies are believed to keep a tally so that when the initial contribution by a reinsurer has been paid back, plus interest, the re-insurer’s interest in the policy ceases or is significantly reduced. This has many of the hallmarks of a loan rather than a life reinsurance contract.
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.