Harbour Asset Management Special Report
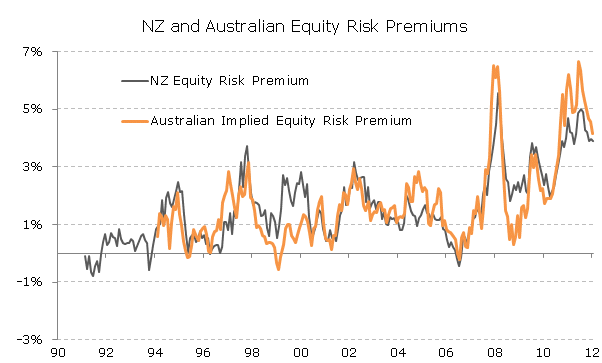
The Equity Risk Premium (ERP) across most equity markets has been elevated since 2010, but started to fall at the end of 2012. In our view, a further normalisation of the ERP would be associated with an out-performance of growth and cyclical stocks. It would also see lower correlation of returns between individual stocks, creating more opportunities for active managers. After the Australian equity market underperformed New Zealand in 2012, we see potential opportunities in Australian stocks moving into 2013, especially if the normalisation of the ERP continues.
Factors explaining the elevated equity risk premium
The ERP quantifies the additional rate of return investors need to compensate for the risk of investing in stocks versus bonds (typically the 10 year bond). ERP are often calculated by taking the forecast earnings yield for the equity market and deducting the 10 year bond yield, although there are many other derivations of this calculation. No matter which way you calculate them equity risk premium are high at the moment.
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.