

Ideas for reforming KiwiSaver
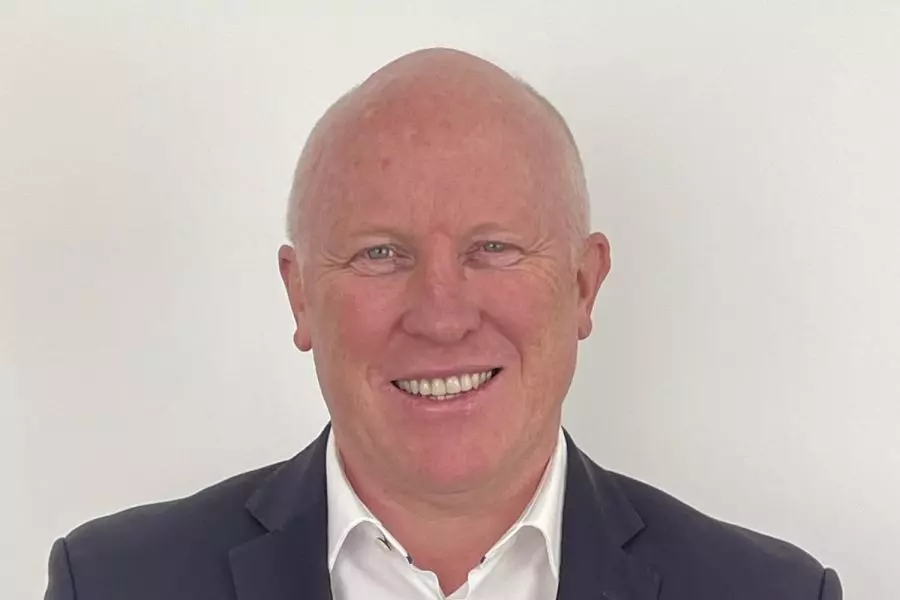
Government focus on reforming KiwiSaver should be “at the point where it makes the biggest impact,” Kernel Wealth founder and chief executive Dean Anderson told an investment conference last month.
But former Mercury Energy chief executive and Fonterra chief operating officer Fraser Whineray said KiwiSaver needs to be reformed with the focus should be on what is politically possible, something that will be durable through successive governments for another 20 years.
“The first question is, can we get it across the political line, and the second question is harder: can it stay over the line,” Whineray told the Investors Association New Zealand (formerly the NZ Shareholders’ Association).
KiwiSaver “is the right thing for the country, it’s long-term and it’s popular,” Whineray said.
“My gut feel is New Zealanders are very focused on fairness,” and will be willing to do their bit to save for retirement as long as they can see their neighbours are doing the same. “They want to know everyone’s doing a bit for themselves.”
Those who oppose compulsory KiwiSaver make some valid points, such as that employer contributions don’t come nowhere and there’s no free lunch or magic money machine, and it’s also likely that compulsion will displace other forms of saving.
“The status quo is untenable. We do need to think about what is a credible alternative. Maintaining the current system is chasing unicorns – it ain’t going to happen.”
Whineray argued that because of the different tax treatment, if the New Zealand system requires 5% contributions from employees plus a 5% contribution from employers, that will be equivalent to the 12% contribution rate in Australia.
“We’re already 70% of the way,” he said, noting that Australia took more than 30 years to reach its current 12% contribution rate. KiwiSaver began in July 2007.
Kernel now has $6 billion in funds under management and more than 80,000 Kiwisaver accounts, having more than doubled in the past 12 months.
Anderson noted that in 1965, there were seven workers for every retiree and that there are now four workers per retiree. In 40 years’ time, there will be just two.
“For most of human history, children have been an asset. Today, a child is one of the biggest purchases you can make.”
Most households require two incomes to support themselves and, globally, no incentive scheme aimed at persuading women to have more children has worked to move the needle, Anderson said.
“We’re lucky enough to be born in New Zealand where the quality of life is better than any king in history.
“As an entrepreneur, I’m confident we can work our way through and we can do it without losing what makes New Zealand unique.”
Anderson noted there’s about $250 billion sitting in household term deposits and savings accounts, which is “greater than the entire stock market. It isn’t doing the work it could be doing for the people who own it or for the country.”
“When more people have savings of their own, we can have sensible conversations about New Zealand Superannuation.
Both Anderson and Whineray think children should be enrolled in KiwiSaver from birth, but Anderson said the number of under-18-year-olds has fallen by half in the last decade. “That should be a red flag.”