

Asset Allocation: Investing in Low, Really Low, Inflationary Environme
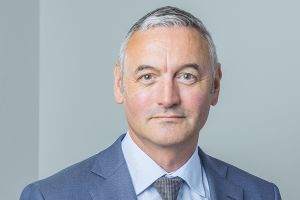
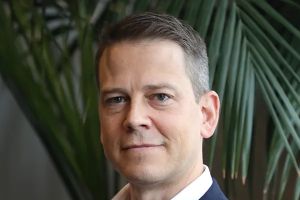
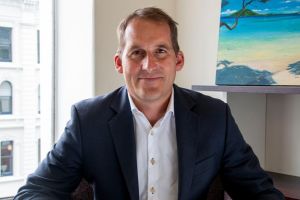
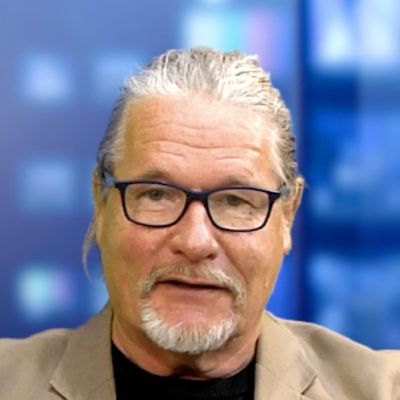
Portfolio construction has, for many years been based on the belief that equity and bond markets are inversely correlated. When one goes up the other goes down. However, for the past year both markets have risen, thus raising a conundrum for advisers and investors. In this article BT Funds Management chief investment officer Craig Stobo (pictured) discusses the implications of this changed relationship for asset allocation, and raises a theory explaining why both markets are moving in tandem.
 Prices for commodities are falling to lows not seen since the 1960s and 1970s.Consumer price inflation in the major developed economies of Europe and the US is benign. In Japan deflationary pressures are still evident across most sectors, including assets such as property despite the large price falls that have already occurred in the 1990s to date. Central banks have won the war against inflation after instituting hawkish monetary policy regimes in the 1980s and 1990s, aided by the waves of deflationary pressures generated by Asia’s excess manufacturing capacity.
This represents a relatively new backdrop for those investors whose experience of markets was affected by the financial market deregulation and asset price boom of the inflationary 1970s and 1980s. During that period, to generalise, investors’ expectations of economic cycles included a traditional monetary response to any unbalanced economic growth which subsequently affected the discounting of company earnings. Or more simply put, interest rates were raised to quell inflationary pressures, and stock prices fell. This negative correlation between interest rates and the equity market served as a useful framework for making stock selection and asset allocation decisions in that period.
Click the button below to subscribe and will have free unlimited access for a limited time to full article and all other articles on the site.
You will also be able to comment on articles on Good Returns.